
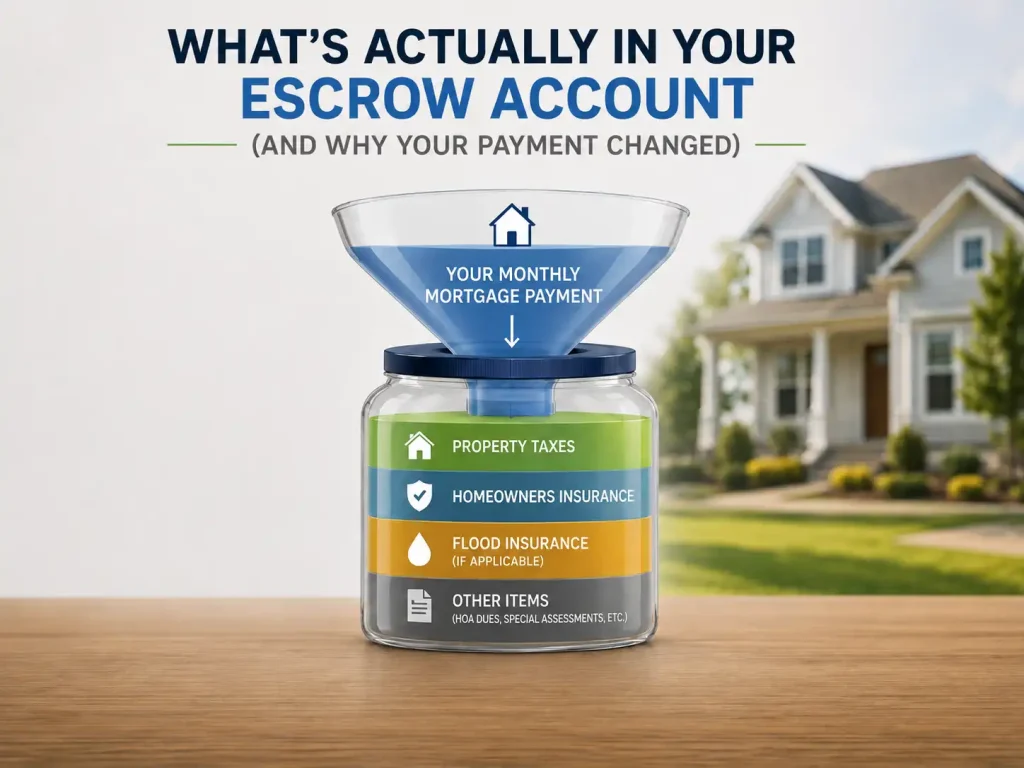
You have a fixed-rate mortgage. Your rate has not changed. And your payment just went up.
This is one of the most common calls we get from past clients, and the answer is almost always escrow.
What escrow does
Your servicer collects a portion of your annual property taxes and homeowners insurance with each mortgage payment, holds it, and pays those bills when they come due.
The purpose is partly convenience and partly the lender protecting its collateral. A house with unpaid taxes or lapsed insurance is a problem for whoever holds the mortgage.
Your rate is fixed. Your taxes and insurance are not. That is why the total payment moves.
The annual analysis
Once a year your servicer reviews the account. They look at what came in, what went out, and what next year’s bills are projected to be.
Then they adjust your monthly escrow portion accordingly, and you get a statement explaining it. Most people file that statement without reading it. It is worth reading.
Why shortages happen
A shortage means the account did not hold enough to cover the bills. There are a few usual causes.
Your taxes went up. The most common reason in New Jersey. Municipal budgets and rates change.
Your insurance premium went up. Premiums have been rising broadly, and a renewal can come back meaningfully higher.
Your first year was estimated. At closing, your servicer projected your taxes and insurance. If the projection was low, the first annual analysis corrects it. This catches a lot of new homeowners, especially where a home was recently assessed after a sale or improvement.
You had a supplemental bill. An added assessment or adjustment can create a bill nobody planned for.
The cushion
Your servicer is generally permitted to hold a modest reserve beyond what is strictly needed, so a timing mismatch does not leave the account unable to pay a bill.
When your projected bills rise, that cushion has to rise too, which is part of why an increase feels larger than the tax increase alone.
Your two options on a shortage
Pay it as a lump sum, which clears the deficit and keeps your ongoing monthly increase to just the higher bills going forward.
Or spread it across the next twelve payments, which is what happens by default. Your payment rises more, but you owe nothing today.
Neither is wrong. If you have the cash and want the lower monthly number, pay the lump sum. If cash is tight, spread it.
Note one thing about spreading it: the following year your payment may drop somewhat, because you will no longer be repaying a shortage on top of your regular escrow.
Surpluses happen too
If the account holds more than needed beyond the permitted cushion, you generally get a refund check.
Do not treat it as found money. It usually means your escrow was over-collected and your payment may adjust downward, or that a bill came in lower than projected and could go back up.
What you can control
Shop your homeowners insurance annually. It is one of the few escrow inputs you have direct influence over, and premiums vary more between carriers than people expect.
Read your annual escrow statement rather than filing it.
And keep some room in your budget for this. A payment that consumes every available dollar has no capacity to absorb a tax increase, and tax increases are a feature of owning here.
Questions about a statement you just received? Send it over and we will read it with you.
Trinity Lending Company | NMLS #2762052 | Equal Housing Opportunity