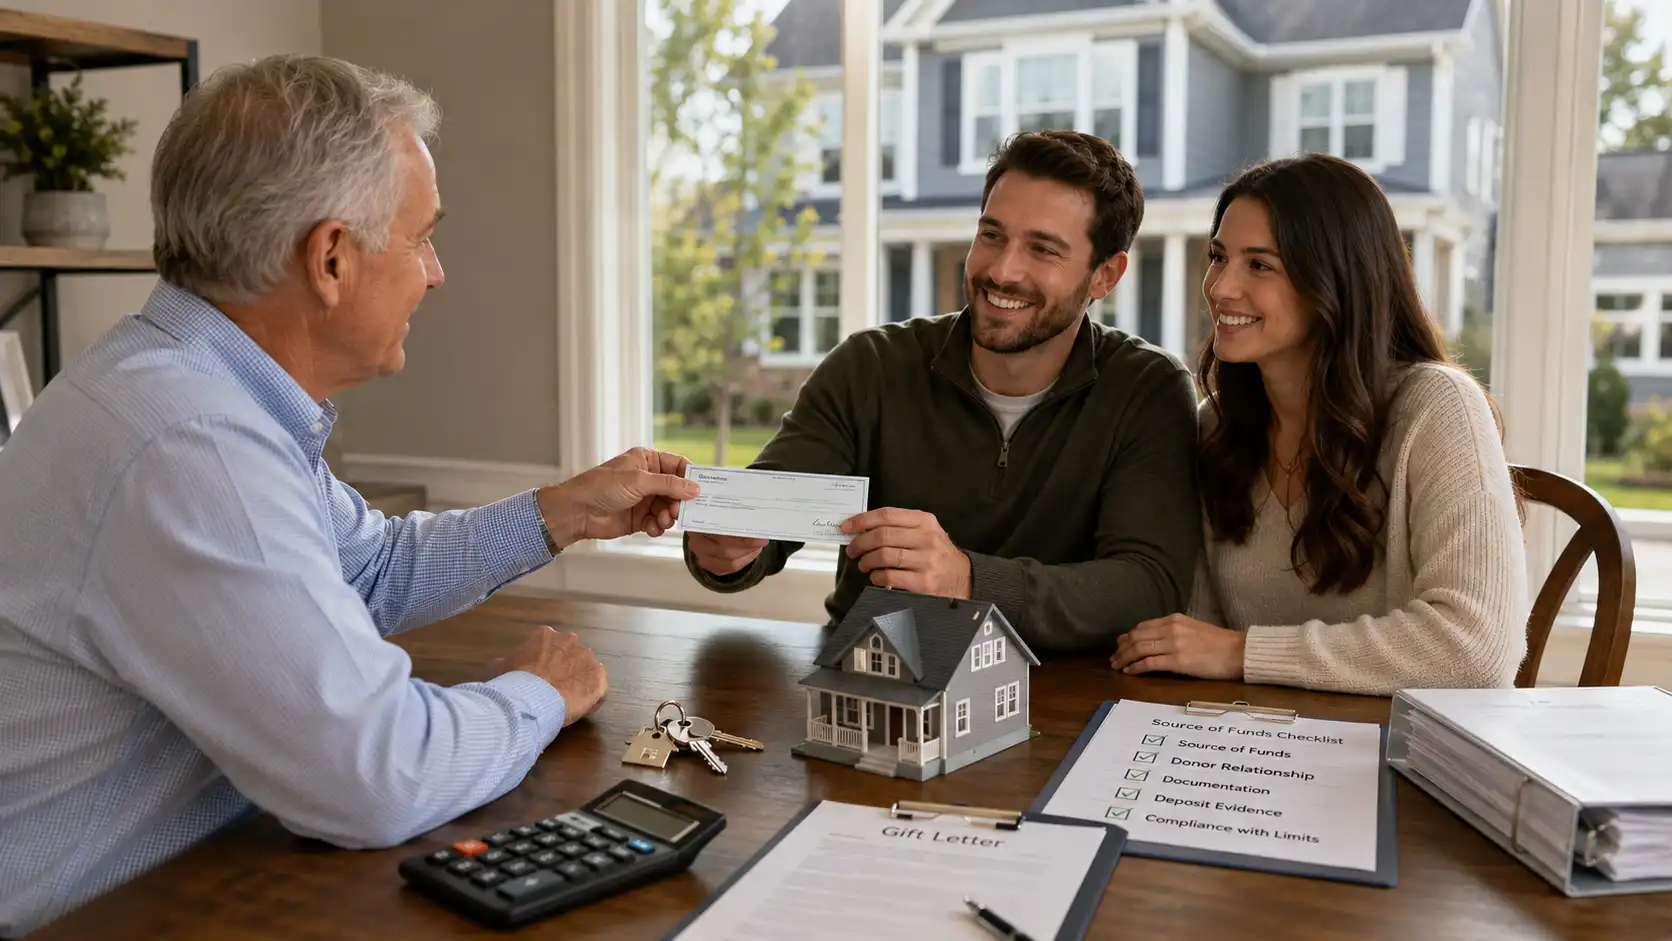
Family help is common, especially for first-time buyers in an expensive market. Lenders permit it. They just want it documented properly.
Do this right and it is routine. Do it wrong and it delays your closing.
Who can give you a gift
Eligible donors vary by loan program. Generally, close relatives qualify across most programs: parents, grandparents, siblings, children, spouses.
Some programs are broader and allow gifts from a fiancé, domestic partner, or someone with a documented close relationship. Some permit gifts from employers, unions, or charitable organizations.
What is generally not allowed is a gift from anyone with an interest in the transaction. That means the seller, the listing agent, the builder, or anyone who benefits from the sale closing. Those are treated differently and are usually prohibited as gift funds.
If your donor is anyone other than an immediate family member, tell us before the money moves.
It has to be a gift, not a loan
This is the requirement that matters most.
A gift means no expectation of repayment. If your parents expect the money back, that is a loan, and an undisclosed loan is a serious problem. It changes your debt obligations and misrepresents your file.
Both you and your donor sign a statement to this effect. Take it seriously.
The gift letter
Your lender will provide a form. It generally needs to include the donor’s name, address, and phone number, their relationship to you, the exact dollar amount, the property address, a statement that no repayment is expected, and signatures from both parties.
Straightforward, and it takes five minutes when everyone knows it is coming.
The paper trail is the real work
The letter alone is not enough. Underwriting needs to trace the money.
That usually means documentation of the funds leaving your donor’s account and arriving in yours. Your donor will typically need to provide a bank statement, which surprises some families who did not expect to share financial documents.
Prepare them for this in advance. A donor who is caught off guard and reluctant creates a delay at exactly the wrong moment.
How to actually move the money
A wire transfer is cleanest. It creates a clear record showing exactly what came from where.
A check works but takes longer to clear and document.
Cash is a problem. If your donor hands you cash and you deposit it, there is no way to trace its origin, and undocumented cash generally cannot be used regardless of where it actually came from.
Also avoid having the money pass through multiple accounts. Every stop adds documentation. Direct from donor to you, or in some cases directly to the settlement agent at closing, is simplest.
Timing
Two workable approaches.
Receive the gift well before you apply, so the funds have been sitting in your account across the statement periods your lender reviews. Money that has been there long enough is generally considered seasoned and draws fewer questions.
Or receive it during the process and document it fully. This works fine, it just means the paperwork happens on a deadline.
What does not work is a large deposit appearing with no explanation. Every unexplained deposit generates a request for documentation, and that request costs you days.
Tell us early
If family is helping, mention it at the pre-approval conversation rather than when the money shows up. Knowing about it upfront means we build it into the file correctly instead of chasing it later.
Trinity Lending Company | NMLS #2762052 | Equal Housing Opportunity