
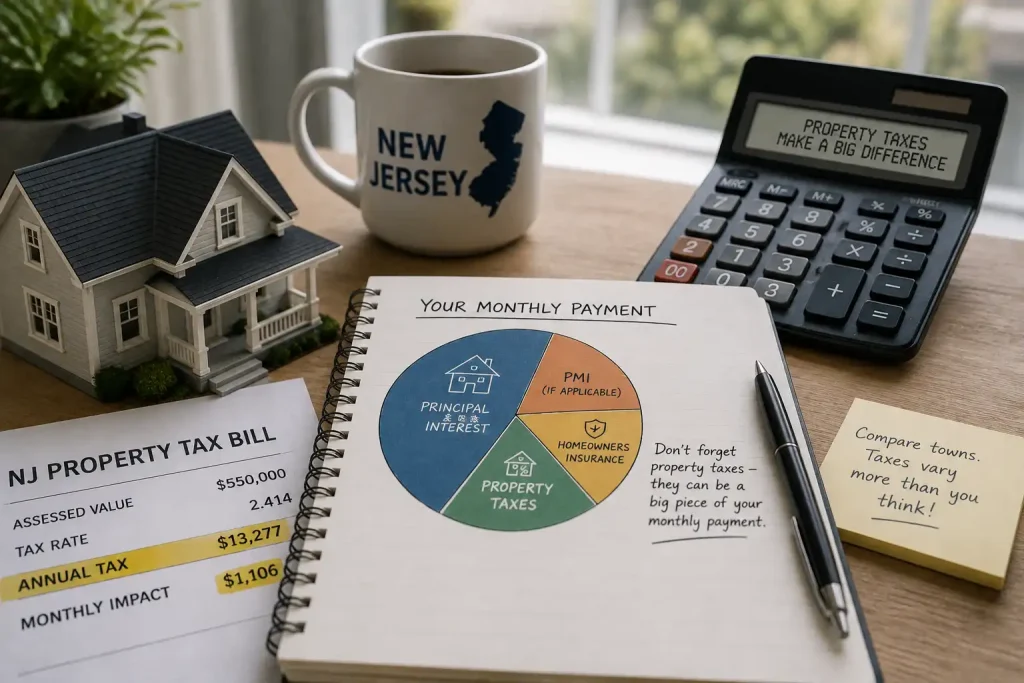
Buyers move here from other states, look at a listing price, and think they know what the house costs. Then they see the tax bill.
New Jersey property taxes are the highest in the country, and they do more than raise your payment. They change how much house you qualify for at all.
Taxes are part of your mortgage payment
Most buyers pay property taxes through escrow. Your annual bill is divided into monthly pieces, collected with your mortgage payment, and held by your servicer until the bill comes due.
So your monthly payment is not just principal and interest. It is principal, interest, taxes, and insurance, and in New Jersey the tax portion can be a large share of the total.
What this does to your buying power
Here is the mechanism that catches people.
Lenders measure your total housing payment against your income. Everything in that payment counts, including taxes. A higher tax bill means less room for principal and interest, which means a smaller loan.
Consider two hypothetical buyers. Identical income, identical credit, identical down payment, identical debts. Buyer A is looking in a town where a home in their range carries a $9,000 annual tax bill. Buyer B is looking where a comparable home carries $16,000.
That is a difference of roughly $580 a month. Buyer B’s approved loan amount is meaningfully lower than Buyer A’s, purely because of the town.
Same paycheck. Less house. Nothing about them changed.
The practical version
This means your budget is not a single number. It is a number per town.
Buyers who get pre-approved for a maximum and then shop across municipalities with very different tax loads end up confused when a house that seemed affordable does not work.
The fix is simple. Once you have narrowed to a few towns, run your numbers in each of them.
Pull the actual bill, not the average
Town averages are useful for narrowing your search and useless for evaluating a specific house.
Within any municipality, individual assessments vary. A recently renovated home may be assessed differently than the one next door. Listing sites are not always current.
Before you write an offer, get the actual current tax bill on that specific property. Your agent can pull it, and it is public record.
Assessed value is not market value
Your assessment is the figure the municipality uses for taxation. It is not necessarily what the house would sell for.
Towns reassess periodically, and assessments can change. Budget with the understanding that your tax bill is not frozen for as long as you own the house. Municipal budgets change and so do rates.
This is also why your escrow payment can rise over time even when nothing about your loan changed.
Build in room
The buyers who struggle are the ones who stretched to the absolute maximum in a high-tax town and left no margin for a tax increase or an insurance premium going up.
Both of those things happen. Leaving cushion is not conservative, it is realistic.
Tell us the towns you are considering and we will run your qualifying number in each one so you know what you are working with before you fall for a house.
Trinity Lending Company | NMLS #2762052 | Equal Housing Opportunity