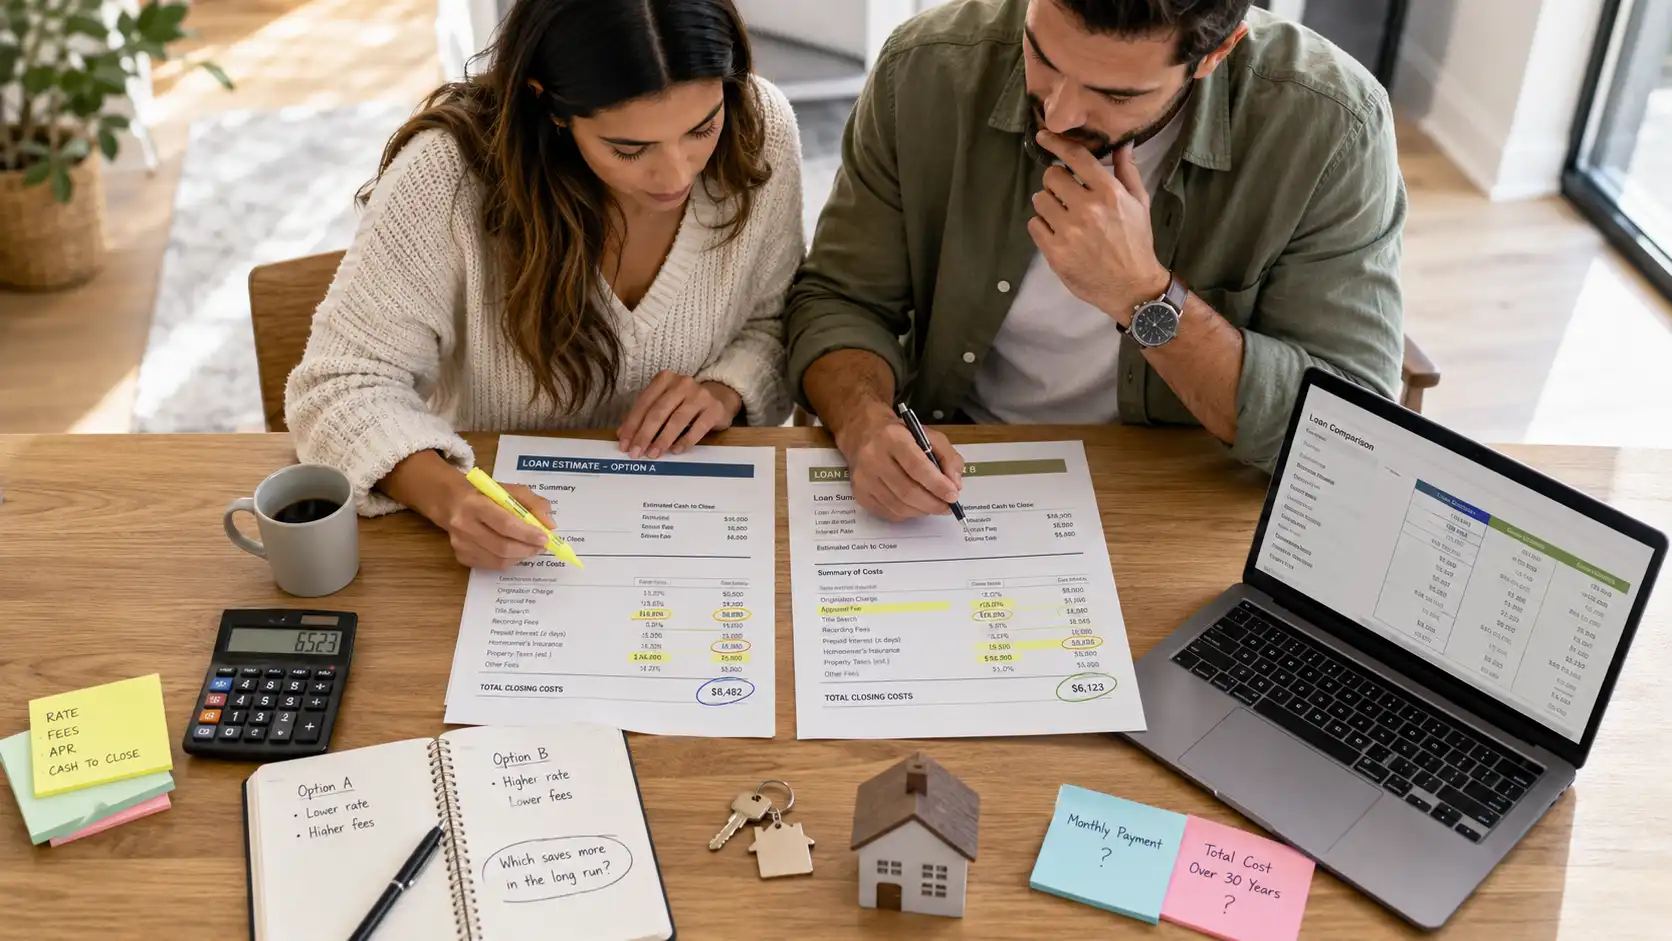
Within three business days of applying, every lender must give you a Loan Estimate. The format is identical across every lender in the country, and that is not an accident. It exists specifically so you can put two offers side by side and compare them honestly.
Almost nobody uses it that way, mostly because nobody explains how to read it.
Page one: the loan itself
The top section covers the basics. Loan amount, term, whether the rate is fixed or adjustable, and whether the loan carries a prepayment penalty or a balloon payment.
Check those last two. Both should generally be “no” on a standard purchase, and if either says yes you want to understand exactly why before going further.
Below that you will find your projected monthly payment broken into principal and interest, mortgage insurance, and estimated escrow. Note that escrow figures are estimates at this stage, and in New Jersey they are the line most likely to shift as actual tax and insurance numbers firm up.
Page two: where lenders actually differ
This is the page that matters for comparison.
Section A, origination charges. What the lender is charging you. This varies significantly between lenders and it is the most useful single comparison on the form. If one lender’s Section A is much higher, ask why.
Section B, services you cannot shop for. Appraisal, credit report, and similar. Less variation here, since the lender selects these providers.
Section C, services you can shop for. Title services and settlement. You have the right to choose your own providers here, and the lender must give you a written list of options. Most buyers never exercise this.
Sections E, F, and G. Government recording charges, prepaid interest and insurance, and your initial escrow deposit. These are largely determined by your property and closing date rather than by your lender, so they should be broadly similar across offers. Big differences here usually mean different assumptions, not a better deal.
The comparison mistake almost everyone makes
Buyers compare the bottom-line cash to close and pick the smaller number.
That is misleading, because cash to close includes your down payment and prepaid escrow, neither of which is a lender charge. A lender using a lower tax estimate will show less cash to close without offering you anything better.
Compare Section A first. Then look at lender credits, which appear as a negative number and reduce your costs in exchange for different loan pricing. Then look at the rate alongside those credits, because a lower rate paired with higher upfront cost is a different product than a higher rate with a credit, not a better one.
Page three: the standardized comparisons
The last page includes figures designed for exactly this purpose. Total payments over five years, how much of that goes to principal, the annual percentage rate, and the total interest percentage.
Those five-year figures are genuinely useful, because most people do not keep a mortgage for thirty years. Comparing what two offers cost over a realistic holding period tells you more than comparing the rate alone.
How to use it
Apply with more than one lender within a short window. Credit scoring models treat multiple mortgage inquiries in a defined period as a single inquiry, so this does not damage your score.
Get the Loan Estimates. Lay them next to each other. Compare Section A, compare credits, and compare the five-year totals.
Then ask questions about anything that differs. A lender who cannot explain their own form clearly has told you something useful.
Bring us an estimate from anyone and we will walk through it with you line by line, including the parts that are not in our favor.
Trinity Lending Company | NMLS #2762052 | Equal Housing Opportunity